Get approved in as little as 24 hours. No setup fees, no hidden costs.
Get Started FreeHigh-Risk Industries · SEO & Web Design
Banks flag SEO agencies, web design studios, and hosting providers for the same reasons: the deliverable is intangible, results take months to show, and revenue bills automatically to stored cards. We underwrite for exactly that profile. Pricing starts at interchange plus 0.80%, with every fee disclosed in the merchant service agreement before you sign.
If a previous processor declined you, froze your funds, or exited mid-retainer, send us your statements with your application. We will tell you what we can place and on what terms before you commit to anything.
Apply online — most merchants are approved within 24 hours.
Be approval-ready
What SEO & web design underwriters ask for
Your terms, before you sign
24 hrs
Most merchants are approved within 24 hours.
0.80%
Pricing starts at interchange plus 0.80%, with every fee disclosed in the merchant service agreement before you sign.
20+
Banking partners, so we can shop your file for the strongest available terms.
Apply
Getting set up
Start with a short online application for your SEO, web design, or web hosting business.
Provide bank statements, processing history, ID, and your client service agreement to support your application.
Our high-risk underwriting team matches your file with the banking partner most likely to approve it.
Accept credit card payments for retainers, projects, and subscriptions through an account built to stay open.
SEO agencies
An agency needs three things working together:
The provider matters less for its logo than for whether its underwriters understand agency billing — variable monthly invoices, long client lifecycles, and payments that are almost entirely card-not-present.
We pair your merchant account with the tools to process card payments online, with 3-D Secure authentication protecting your clients' card data and real-time monitoring to prevent fraud before it reaches your dispute ratio.
Web design
Web design billing carries its own risk profile:
Because nearly every payment is card-not-present, banks classify design studios as high-risk by default.
We underwrite around those realities. Deposit and milestone billing structures are supported from the start, and we help you document scope approvals and sign-offs so that when a dispute arrives, it is winnable. Processing stays stable whether you invoice one-off rebrands or run a productized subscription design service.
What's included
Web hosting
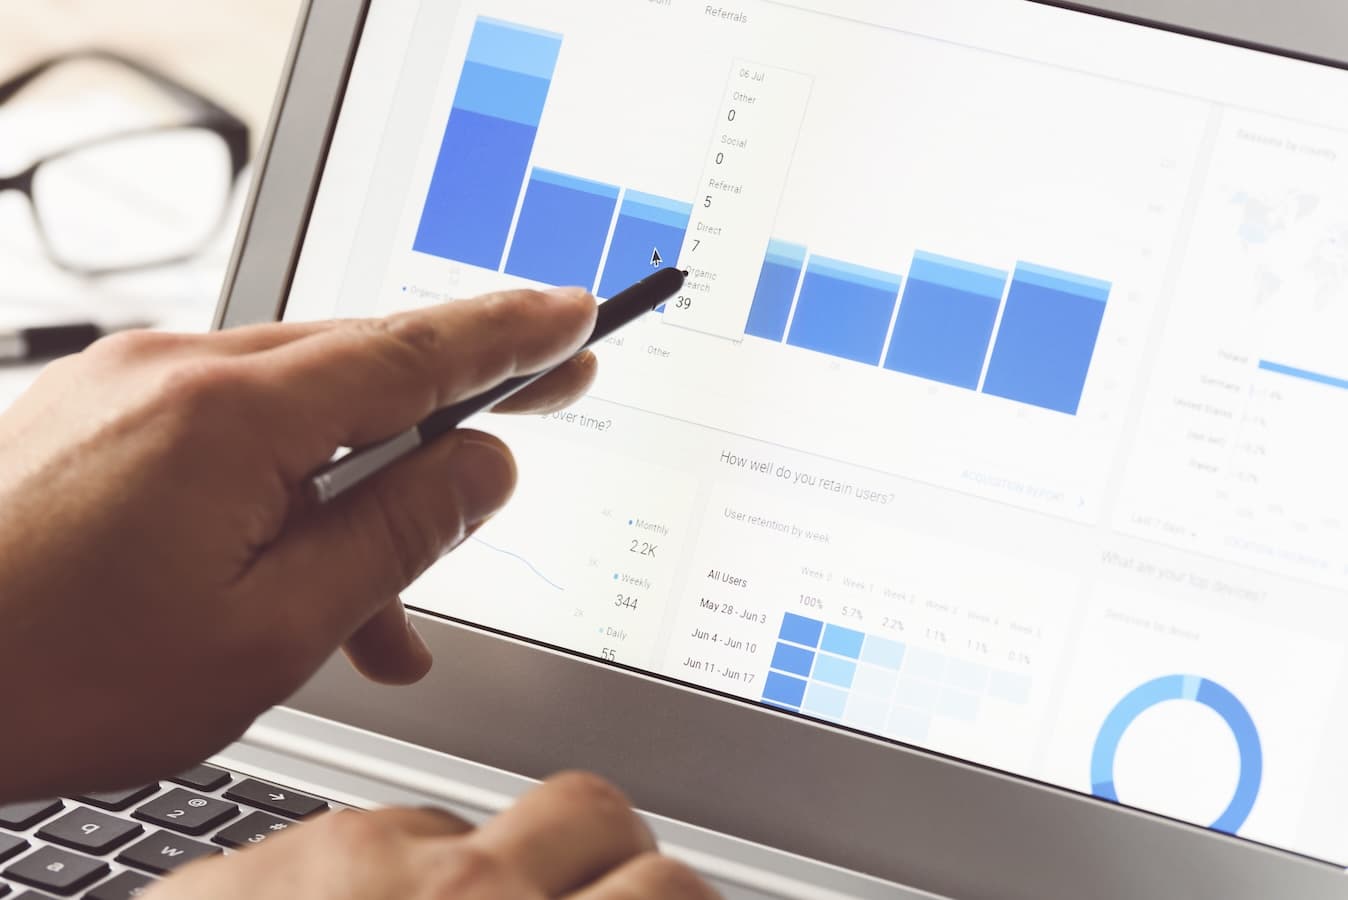
Hosting companies share the recurring-subscription risk profile that gets agencies declined, with wrinkles of their own:
Add free-trial funnels and reseller arrangements, and most mainstream processors decline hosting providers outright.
We underwrite on your actual numbers — subscriber churn, renewal cadence, refund policy, and historical dispute ratio — and configure the gateway for automated renewals and dunning, with alerts that surface a spike in chargebacks before it threatens the account.
Whatever you sell, it fits under one account:
Choosing a processor
Four criteria decide it:
The real fork in the road is aggregator versus dedicated merchant account.
Aggregators onboard you in minutes but pool thousands of merchants together, so one dispute-heavy month can freeze your funds with no warning and no appeal. A dedicated account is underwritten to your business: limits, reserves, and pricing reflect how you actually bill, and the terms are set out in writing before you sign. Here is how the two approaches compare:
The difference
Built for the businesses other processors turn away.
FAQ
Everything you need to know about high-risk payment processing
The deliverable is intangible and results take time. A client who pays for link building or an ongoing strategy may not see measurable return for months, and some dispute the charge with their bank rather than raising it with the agency. Because monthly retainers billed to stored cards are standard, one wave of disputes can destabilize an account quickly without underwriting built for the industry.
Pricing starts at interchange plus 0.80%, with every fee disclosed in the merchant service agreement before you sign. Your exact rate reflects what underwriters review: monthly volume, average ticket size, chargeback and refund history, time in business, and whether you bill one-time projects or monthly retainers on a recurring billing merchant account. Agencies with clean processing history and signed contracts generally qualify for more competitive terms; newer businesses may start with a reserve requirement that relaxes as history builds. Because we work with more than 20 banking partners across the high-risk industries we serve, we shop your file for the strongest available terms rather than forcing every merchant into one pricing model.
The easiest account to get — and, more importantly, to keep — is one underwritten for your actual risk profile. A mainstream flat-rate account may approve you in minutes, then close months later when disputes arrive. With a complete file — a government-issued ID, a voided check, three months of bank statements, processing statements if you have them, and your client service agreement — most merchants are approved within 24 hours, and the account is built to stay open.
A merchant account is where settled card funds sit before reaching your business bank account. For an agency, the distinction that matters is dedicated versus pooled: a dedicated account carries limits, reserves, and pricing tied to your own processing history, so another merchant's bad month cannot freeze your funds.
Every invoice should describe the specific work covered in that billing period. Contracts should be signed before any card is charged, with pricing, payment schedule, and early-termination terms spelled out. For agencies selling digital services through an online checkout, we integrate authentication and address verification so the cardholder is verified at the point of sale. Clear communication with clients about upcoming charges remains the least expensive fraud prevention measure available.
Yes. Many agencies bill both ongoing retainers and discrete digital products — themes, licenses, consulting packages — and each transaction type carries a different chargeback profile. We configure a single merchant account to handle the mixed revenue structure, so monthly retainers and one-time ecommerce builds settle through one stable account with clear reporting by service line.
See how PayKings supports adjacent verticals and the payment solutions that pair with them.
